VLIBRAMMXXVI · 2026
Personal Quant Lab
 Tab. V
A quant research platform that runs locally. Swapping the model doesn’t mean rewriting the backtest, and the backtest keeps to real trading rules: costs, T+1, limit-ups and suspensions.
Brief
Many backtests look good because they peek at the future, or assume any price can be filled. I wanted a research bench I could trust: change the model without rewriting the backtest, and get results that hold up to questions.
Process
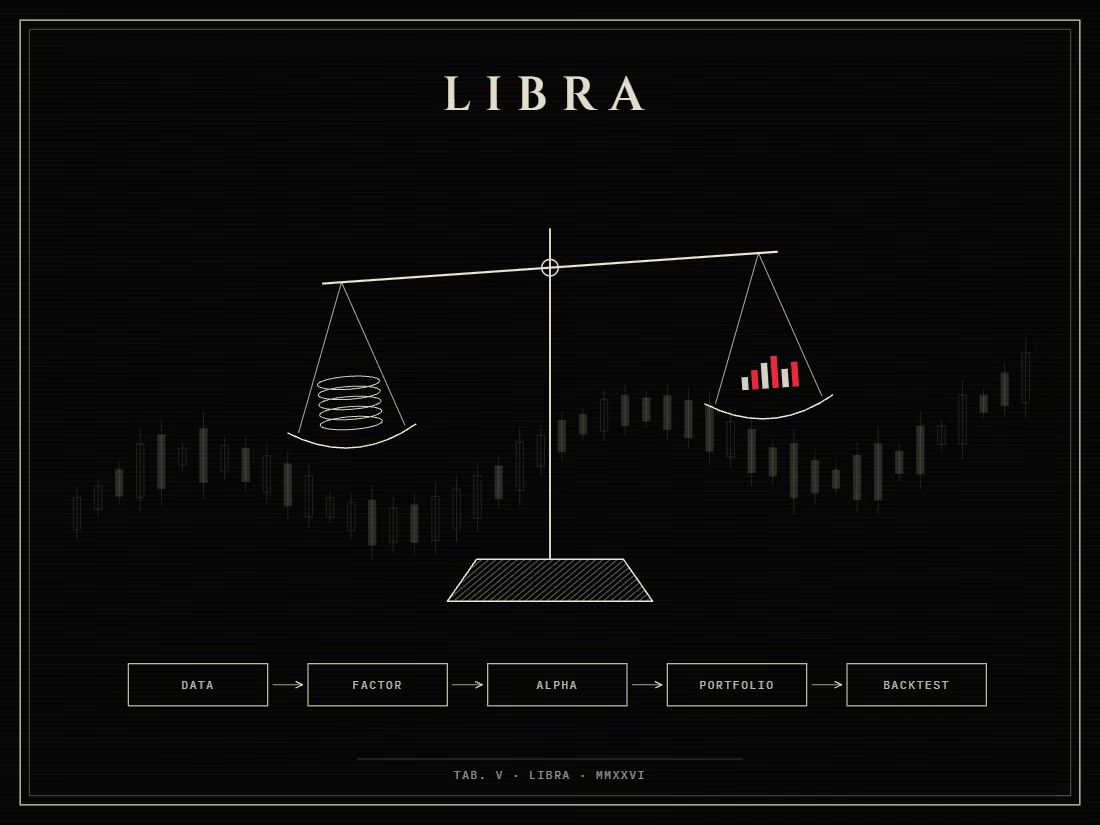
The chain is split into stages: data sources, factors, alpha models, portfolio strategy, backtest engine, metrics and reports. An alpha model only has to output three columns, date, symbol and score, so single factors, composite factors and even another model’s prediction files all plug into the same portfolio and backtest.
Trades fill at the next day’s open, with commission, stamp duty, slippage and market impact counted, and the backtest respects T+1, board lots, no buying at the limit-up, no trading while suspended, and turnover capacity. A separate backtest-integrity policy says that a high-return result without enough evidence cannot become the main strategy.
Every run goes into a local registry: tasks, events, artifacts, dataset fingerprints and experiment lineage, along with the Git commit at the time and whether there were uncommitted changes.
Outcome
It is for research and isn’t connected to live trading. Past backtests don’t promise future returns, so no return figures appear here.